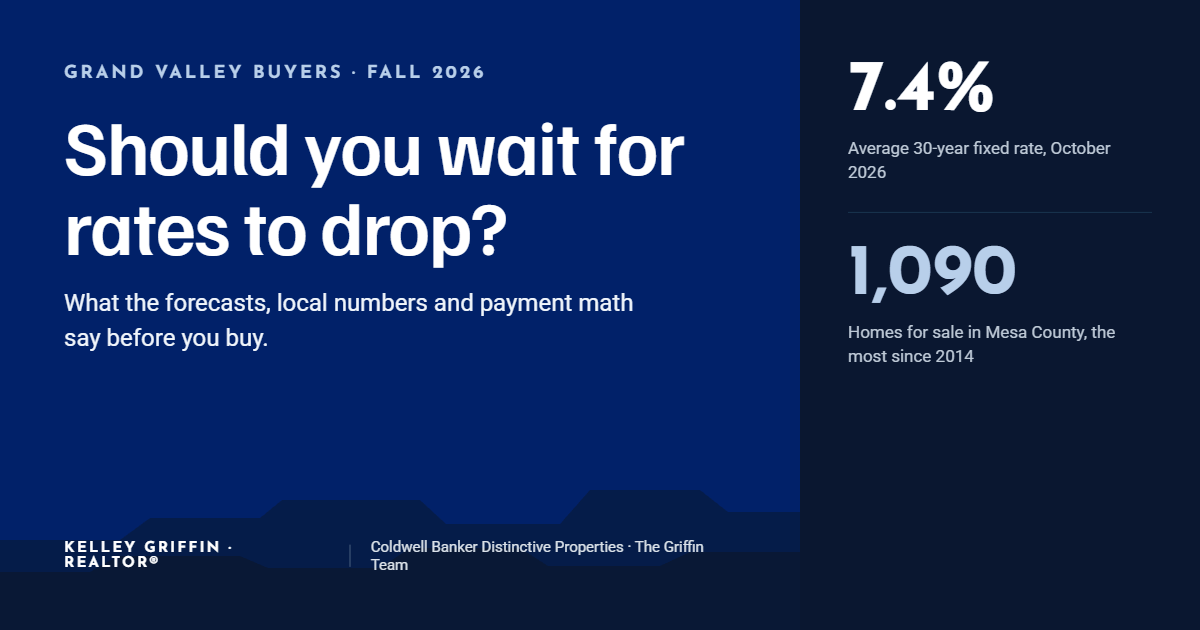
Should you wait for rates to drop?
Blog Kelley Griffin October 21, 2026
Blog Kelley Griffin October 21, 2026
Oct 21, 2026 · @Kelley
For most Grand Valley buyers, waiting for rates to fall is a gamble with poor odds right now. The major forecasters expect 30-year rates to stay above 7% through 2027, while local inventory is the highest it has been since 2014. That combination means more choice and more negotiating room today, and no clear payoff for sitting on the sidelines.
That said, the right answer depends on your timeline, your savings and your job. Below, I walk through where rates are headed, what our local market is doing, and the actual dollars at stake, so you can make the call for your own situation.
I'm Kelley Griffin, a Realtor with Coldwell Banker Distinctive Properties and The Griffin Team, helping buyers and sellers across Fruita, Grand Junction, the Redlands and the Grand Valley.
Rates have moved up this fall, not down. Freddie Mac's weekly average for a 30-year fixed was 7.28% on October 1 and 7.40% on October 8, compared with 6.34% a year earlier. The Federal Reserve raised its benchmark rate in mid-September, and its next meeting is October 27–28.
The forecasts that lenders watch have shifted the same way:
Forecasts are not guarantees, and they have been wrong in both directions. But when the two biggest forecasters both revise up, "rates will be lower by spring" is a hope, not a plan.
Higher rates have slowed sales, and that has handed buyers more choice than they've had in over a decade. Here is Mesa County as of the September 2026 Bray Report:
Measure | September 2026 | Change vs. Sept 2025 |
|---|---|---|
Active listings | 1,090 | Up 34.7%, highest since Nov 2014 |
Closed sales | 197 | Down 7.5% |
Median sale price | $414,000 | Up 1.4% |
Active listings were spread across the valley: 173 in North Grand Junction, 136 in the Redlands and 133 in Fruita. In August, homes took a median of 65 days to sell, up from 59 a year earlier, and supply reached 4.4 months, the most since early 2017.
Two things stand out. First, prices haven't dropped. They've held roughly flat, so waiting for a "crash" isn't supported by the local numbers. Second, sellers are negotiating. In Grand Junction, more than half of recent sales (57.7%) closed under list price, per Zillow.
Conditions vary by price range. Homes under $500,000 still move faster, while higher price ranges have more supply and more room to negotiate.
Every 1% drop in rate saves about $250 a month on a typical Mesa County home. Here's the example: a $414,000 home (the county median) with 10% down, so a $372,600 loan on a 30-year fixed.
Rate | Monthly principal & interest | vs. today (7.4%) |
|---|---|---|
6.4% | $2,331 | $249 less |
6.9% | $2,454 | $126 less |
7.4% | $2,580 | — |
7.5% | $2,605 | $25 more |
Principal and interest only; taxes, insurance and any mortgage insurance are extra. Your lender can give you exact numbers.
Now weigh that against what waiting can cost you:
The saying "marry the house, date the rate" holds up here. You can refinance later if rates drop, though refinancing has its own costs and no one can promise when, or if, it will make sense. You can't go back and renegotiate the purchase price.
In a market with this much inventory, you have tools that buyers didn't have a few years ago:
Which of these makes sense depends on the specific home and seller, and that's where a local agent earns their keep.
Buying now isn't right for everyone. Waiting can be the smart move if:
The key is that these are reasons about your situation, not predictions about rates. If you're ready on those fronts, today's market gives you room to buy on good terms.
Will mortgage rates go down in 2027? The major forecasters don't expect much relief. As of October 2026, Fannie Mae projects about 7.5% through 2027 and the Mortgage Bankers Association expects rates to stay above 7%.
Are home prices dropping in Grand Junction? Not meaningfully. The Mesa County median sale price was $414,000 in September 2026, up 1.4% from a year earlier. What has changed is the number of homes for sale and how long they take to sell.
Is it a buyer's market in Mesa County? It's shifting that way. Inventory is the highest since 2014, and more than half of recent Grand Junction sales closed under list price. Homes under $500,000 remain more competitive than higher price ranges.
Can I get the seller to pay for a lower rate? Often, yes. Seller-paid buydowns and closing cost credits are common requests in this market. Whether a seller agrees depends on the home and how long it has been listed.
Should I buy now and refinance later? It can work, but only if the payment is comfortable at today's rate. Treat a future refinance as a possible bonus, not something your budget depends on.
What's the first step if I'm thinking about buying? Talk to a local lender to get pre-approved and see your real numbers, then sit down with a local agent to look at what's available in your price range and preferred areas.
Every buyer's situation is different, and the right answer for you depends on your budget, your timeline and the specific homes available. I'm happy to sit down, walk through what's on the market in your price range, and connect you with a trusted local lender so you can see your real payment.
Kelley Griffin · Realtor, Coldwell Banker Distinctive Properties · The Griffin Team Serving Fruita, Grand Junction, the Redlands and the Grand Valley theGriffinTeam.com
This article is for general information only and is not financial or lending advice. Rates and market data are as of October 2026 and change frequently. Equal Housing Opportunity.
Stay up to date on the latest real estate trends.
Blog
Why now might be the best time to buy
Blog
A local look at the lifestyle, community, and livability that set Fruita apart
Blog
Life with three little boys is naturally a bit wild.
Blog
A family's dream cabin on the Grand Mesa becomes a reality.
We live, work, and serve in the community we love. Our deep market knowledge means smarter pricing, stronger offers, and confident decisions.
THE GRIFFIN TEAM
COLDWELL BANKER DISTINCTIVE PROPERTIES
Agent phone: 970-589-6555
Office Phone: 970-243-0456
131 N. 6th Street Grand Junction, CO 81501